Research note. China is experimenting with a new way of packaging access to artificial intelligence: instead of treating AI only as a chatbot, an application or a cloud subscription, companies are beginning to present the underlying computing capacity as a measurable benefit. Banks attach model allowances to credit cards, telecommunications operators sell monthly token plans, and restaurants and bars use AI access as a customer incentive. The phenomenon is still early and uneven, but it reveals an important change in the commercial language of AI: computing power is moving from the infrastructure layer into ordinary transactions.
Tokens are not money — they are a unit of AI work
An AI token is a small unit of text, code or other input that a model processes. When a user asks a question, uploads information or requests an image, the system converts the request into tokens, performs computation and often returns an output that is also measured in tokens. The analogy with mobile data is useful because both are metered resources, but it has limits: a token is not a cryptocurrency, it is not a stable monetary unit and it does not have the same value across models. Tokenization rules, context length, input and output pricing, modality and model architecture all affect how much work a given request represents. The South China Morning Post describes tokens as the basic units that AI systems process or generate, a definition that helps separate the technical resource from the promotional language now surrounding it.
That distinction matters because the phrase “millions of tokens” can sound more like money or stored value than a consumption quota. One million tokens may represent a very large amount of text for one model and a much smaller amount of multimodal or agentic work for another. A plan that looks generous on paper may be less generous once a user asks an agent to maintain context, call tools, generate images or process video. The first task in analyzing China’s experiment, therefore, is not to accept the token as a new currency but to understand it as an accounting layer: a way for providers to meter demand, subsidize adoption and compare access across products.
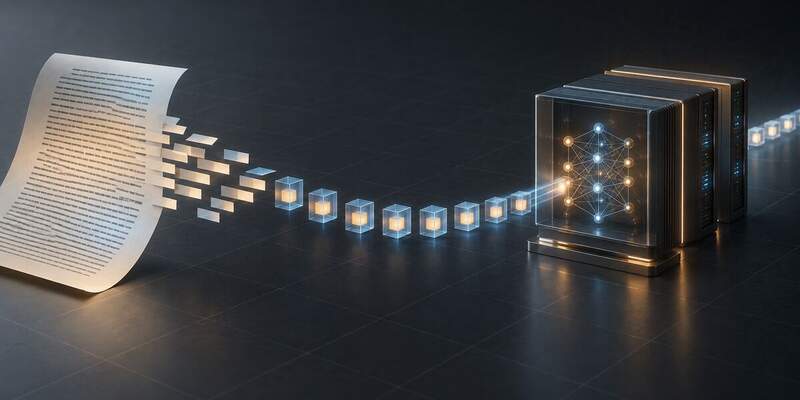
Tokens make a model’s unit of work—and part of its computing cost—visible.
From mobile data plans to model access
The clearest example comes from telecommunications. For decades, mobile operators taught consumers to understand connectivity through minutes, messages and gigabytes. China’s carriers are now testing whether the same habit can be extended to AI. According to China Telecom’s official announcement, the company launched trial Token plans for individual and household users as well as developers and small businesses. The offer combines tokens with connectivity and security, and the company says it is integrating its own models with third-party systems and cloud-computing resources. The commercial logic is significant: the operator is not merely providing a pipe through which another company’s AI travels; it is trying to become the provider that bundles the network, the model, the account and the security layer.
Reporting by TechNode and the South China Morning Post indicates that China Telecom’s household packages begin at 9.9 yuan per month for 10 million tokens, while higher tiers offer larger allowances. The same reporting describes packages for developers and businesses that combine a larger token balance with features such as faster connectivity and security. China Mobile and China Unicom have tested comparable offers. These prices should not be interpreted as a universal cost benchmark because the included models and usage conditions differ, but they show how quickly the unit of sale is changing: a family plan can begin to resemble a small monthly budget for model access.
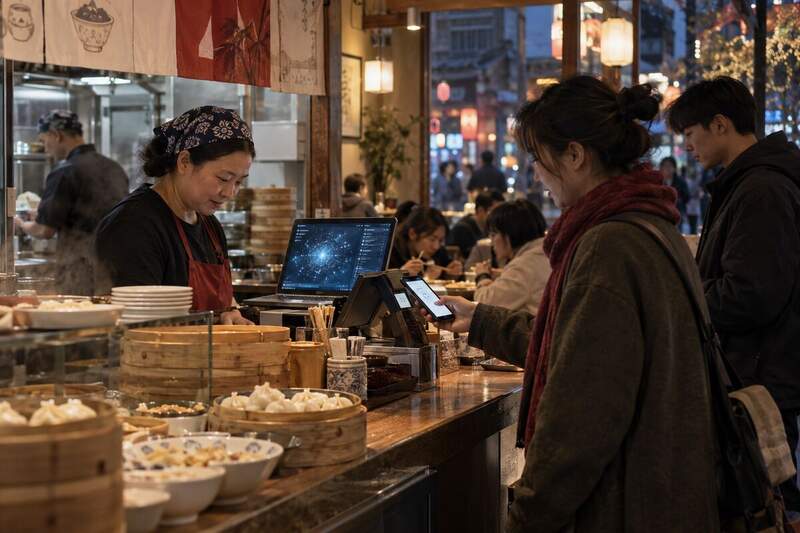
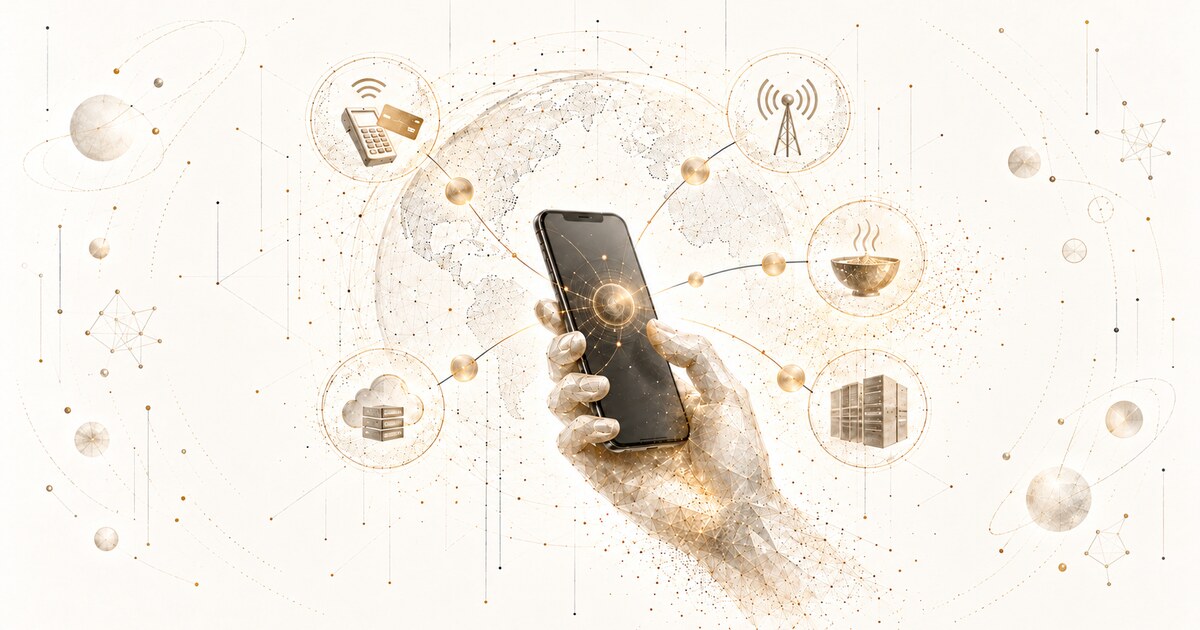
Computing credits are becoming a service connected to everyday uses.
Credit cards that reward computing power
The second channel is financial services. Rest of World reports that China Merchants Bank introduced a credit card aimed at AI developers with benefits tied to MiniMax models, while Shanghai Pudong Development Bank offered a competing package connected to Alibaba’s Qwen models. The reported allowances reach 1.8 billion and 3 billion tokens respectively for qualifying users and transactions. In July, Moonshot AI also partnered with the Agricultural Bank of China and American Express on a card associated with its Kimi model. The key innovation is not the physical card; it is the transformation of model capacity into a reward category alongside cashback, airline miles or shopping points.
This approach solves a distribution problem for AI companies. Many users are curious about models but do not know which plan to buy, how much usage they need or why one provider’s token price should matter. A bank can reduce that friction by putting access inside a familiar financial product. The incentive also encourages repeated use: a customer does not simply receive a one-time trial but accumulates a balance through spending. Yet the arrangement creates an important asymmetry. The reward is easy to advertise, while its actual value depends on model quality, expiration rules, access conditions and whether the user can move the allowance between services. What looks like a large number can therefore function more like a marketing coupon than a liquid asset.
When restaurants and bars become AI distribution points
The most visible examples are deliberately ordinary. In Beijing, the Jingu Yuan dumpling restaurant has reportedly given diners computing credits after a meal; China Minutes describes vouchers worth 10 yuan and a promotion that has distributed roughly one hundred vouchers a day across two branches. The restaurant’s audience includes students, researchers and technology workers, so the offer is not as random as it first appears. The token becomes a bridge between a familiar physical ritual and a digital service that customers already use. Instead of a discount or souvenir, the restaurant gives away a small amount of future computing.
The same logic appears in Beijing’s AGI Bar. According to Reuters and the South China Morning Post, customers who buy a drink and connect to the bar’s Wi-Fi can access AI models, including a local deployment of DeepSeek V4 Flash supported by Nvidia DGX Spark computers. The bar is not simply selling beer with a technical novelty attached; it is turning access to compute into an atmosphere, a meeting point and a reason to return. These experiments matter because they make AI tangible without requiring the customer to visit a cloud console or understand an API. They also expose the economics of the model: the “free” tokens still have to be paid for through hardware, electricity, network capacity and operator subsidies.
Why China is packaging AI this way
The commercial context helps explain the speed of these experiments. China has a large population of mobile-first users, strong super-app distribution and intense competition among domestic model providers. Lower token prices make it possible to subsidize access in places where a Western provider might sell a conventional subscription. A bank can acquire or retain customers with model credits; a telecom operator can increase average revenue per user by adding compute to connectivity; a restaurant can differentiate itself with an unusual promotion; and a model company can place its system in front of people who might never search for it directly. The same token can thus perform several jobs at once: it is a unit of consumption for engineers, a reward for cardholders, a promotional object for merchants and a distribution mechanism for model providers.
The policy environment also points toward a broader service strategy. In June 2026, Reuters reported that China’s Ministry of Commerce announced 17 measures intended to promote the integration of AI into consumer goods and services, including retail and daily-life applications. The measures do not prove that every token promotion is centrally coordinated, but they show that AI adoption is being framed as a consumption and service question, not only as a laboratory or industrial question. That framing creates room for operators, banks, retailers and local businesses to compete over the last mile of AI: the moment when a person encounters a model as part of an ordinary transaction.
Behind a token allocation are chips, energy and networks.
The infrastructure beneath the promotion
None of this works without a large supply of affordable computation. Token plans are commercially attractive only when providers can estimate demand, route requests across models and manage peak usage without destroying margins. China Telecom’s official description of its Token ecosystem refers to a combination of models, cloud resources, security and cross-application portability. That is a clue to the real strategic objective. The token is useful to the provider because it standardizes a complex backend into a unit that can be packaged, priced and exchanged across an ecosystem. For the customer, the unit is valuable only if it leads to a reliable result: a response, a piece of code, an image, an agent action or another service that solves a problem.
This is also why tokens may become a competitive battleground even when users never see them. Model providers can reduce prices, offer promotional allowances and move consumption toward their own ecosystems. Telecom companies can bundle access with connectivity. Cloud platforms can aggregate multiple models behind one account. In May 2026, Reuters reported that China was exploring futures contracts based on AI tokens, although the idea was still at an early stage and subject to uncertainty. Whether or not such a market develops, the proposal reveals how seriously the token is being considered as a way to measure and manage the cost of computation.
Limits, risks and the problem of comparability
The most important limitation is that token balances are not automatically comparable. A token is produced by a tokenizer and consumed within a model-specific pricing system; it is not a universal unit like a kilowatt-hour. Chinese-language prompts may split differently from English prompts, images and video can have different accounting rules, and agents may use many hidden calls while completing one visible task. Consumers may also misunderstand what “unlimited” means if a bar or subscription applies rate limits, selected models, fair-use rules or a short validity period. Transparent disclosure would therefore need to show which models are included, whether input and output tokens are counted separately, when the balance expires, whether it can be transferred and what happens when the provider changes the model.
There are also governance and market risks. A token reward can lock a user into one model ecosystem, turn a financial product into a channel for behavioral profiling and make the cost of AI appear smaller than it really is. Resale markets may create account-sharing and security problems, while promotional access can encourage people to send sensitive information to a model simply because the computation feels free. Providers should distinguish a discount from a financial instrument, publish meaningful usage conditions and avoid presenting model capacity as if it were cash. Regulators and researchers should pay attention to the same questions that matter in telecommunications and digital payments: transparency, portability, consumer protection, data use and the ability to leave an ecosystem without losing accumulated value.
A new accounting layer for the AI economy
China’s experiment is best understood neither as a sudden creation of a new currency nor as a collection of amusing promotions. It is an attempt to turn an invisible production cost into a visible product surface. Once computation can be counted, it can be bundled with a phone bill, attached to a credit card, offered with a meal or used as a signal in a lending decision. That makes AI easier to sell, but it also changes the relationship between providers and users: the customer is encouraged to think not only about what an application does, but about how much model capacity it consumes and which ecosystem supplies that capacity.
The long-term outcome is not yet settled. Token plans may remain a short-lived subsidy while providers search for better pricing models, or they may become a durable layer of digital commerce alongside data plans, loyalty points and cloud subscriptions. The answer will depend on whether providers can make the unit understandable, portable and tied to outcomes that users recognize. The central lesson is already clear: the next phase of AI competition will not be fought only inside models. It will also be fought in the everyday channels that distribute them—banks, telecom operators, shops, restaurants, workplaces and the devices people already carry.
How to read the evidence
The cases examined here should be understood as market experiments rather than proof that a standardized token economy already exists. The evidence comes from a combination of official company material, reporting by specialist technology outlets and accounts of consumer-facing pilots. These sources answer different questions. A corporate announcement describes the product a provider wants to distribute; a technical publication can clarify its pricing and architecture; and independent reporting can show how the offer is presented in the street, in a bank or in a restaurant. Comparing those layers is essential because the promotional language may be broader than the actual service. A serious assessment therefore needs to separate what has been announced, what has been tested and what can be verified from the experience of users.
This distinction also limits what can be inferred from the reported numbers. A package of 10 million tokens demonstrates that a provider is willing to express capacity in that unit, but it does not establish how many users will consume the full allocation or what the effective cost per task will be. A credit-card reward measured in billions of tokens signals an attempt to make AI capacity attractive as a financial benefit, but it does not prove that the reward has equivalent value across models. The most defensible conclusion is narrower: banks, telecom operators and businesses are experimenting with tokens as a distribution and accounting mechanism. Whether that mechanism becomes durable depends on retention, reliability, profitability, consumer comprehension and regulation.
What would show that the model is becoming durable
Several indicators could reveal whether the experiment is moving beyond publicity. The first is repeat use: customers should continue using the benefit after the initial promotion ends. The second is operational reliability: model access must remain available during periods of high demand, and deductions from the balance must be understandable. The third is economic sustainability: providers must show that the revenue generated by the bundle can support hardware, energy, network and support costs without relying indefinitely on subsidies. The fourth is task diversity. If users consume the allocation only for novelty demonstrations, the plan may be a marketing campaign; if they use it for work, study, customer service and automation, it is more likely to represent a real service category.
Durability would also require a clearer relationship between the token and the result. Customers do not ultimately want to buy abstract computation. They want a translated document, a useful answer, a completed workflow, an image, a piece of code or a faster business process. Providers that can explain how a quota supports those outcomes will have a stronger proposition than companies competing only with larger balances. This is particularly important for small businesses, which may lack the technical staff needed to monitor consumption. A successful commercial package will make cost predictable without pretending that every task consumes the same amount of capacity.
The institutional question: who controls the layer?
The expansion of token programs could shift power toward intermediaries that control billing and distribution. A telecom operator, bank or large platform can decide which models are included, how the balance is replenished and which data is shared with partners. That position can create efficiency, but it can also make the intermediary a gatekeeper between users and AI providers. The governance question is therefore not only whether tokens are transparent to the customer, but also whether the customer has meaningful alternatives. A person should be able to understand which company is responsible for the model, which company handles the payment and which company answers a complaint. Clear responsibility becomes more important when a single package combines connectivity, financial services, cloud capacity and automated decisions.
In Latin America, this issue would be especially relevant because many users access digital services through a small number of dominant platforms or mobile operators. A token reward could lower the barrier to using AI, but it could also concentrate access and data in the hands of the companies that already control the customer relationship. Public and private actors should evaluate whether a program promotes genuine access, supports local businesses and respects data-protection obligations. Partnerships with universities, cooperatives and small-business networks could distribute capacity more broadly than a model limited to premium financial products. The objective should be to make AI useful and understandable, not simply to create another closed balance that expires inside one ecosystem.
Conclusion: the value is in the service, not the number
China’s token experiments matter because they show a possible route from artificial intelligence infrastructure to ordinary consumption. Banks, operators and merchants are testing whether computing power can be packaged like data, points or other services people already know. The experiment is still too young to support claims about a universal standard or a new form of money. It does support a more precise observation: tokens are becoming a commercial language for allocating scarce model capacity, subsidizing adoption and organizing relationships between providers and users.
The next stage should be judged by the quality of the contract behind the number. A useful program will disclose what the balance buys, protect the customer’s data, explain expiration and restrictions, support comparison and connect the quota to outcomes. A misleading program will rely on enormous figures, obscure the limits and encourage customers to confuse service credits with money. The strategic lesson for companies and regulators is straightforward. The token may become an important accounting layer, but it will create lasting value only when it helps people complete meaningful tasks under conditions they can understand and trust.